 listicle
Alternatives to Property for Bail Bond Collateral
Table of Contents
- Understanding Bail Bond Collateral Alternatives
- Types of Collateral for Bail Bonds Beyond Real Estate
- How Much Do Bail Bonds Cost Without Property Collateral
- Using a Co-Signer or Indemnitor
- Bail Bond Payment Plans for Flexible Financing
- Legal Alternatives: Bail Reduction and Release on Own Recognizance
- What to Know About Non-Property Collateral Risks
- Frequently Asked Questions
Last Updated: October 3, 2026
Understanding Bail Bond Collateral Alternatives
Bail bond collateral alternatives exist because most people don't own real estate or can't risk pledging it. Understanding non-property options matters for defendants facing real financial constraints.
A bail bond is a financial guarantee that the defendant will appear in court. The bail agent takes on the risk in exchange for a fee. When you lack property equity, other assets and arrangements can serve the same purpose. Alternatives range from cash payment to co-signer agreements and payment plans, each with distinct advantages, costs, and risks.
Types of Collateral for Bail Bonds Beyond Real Estate
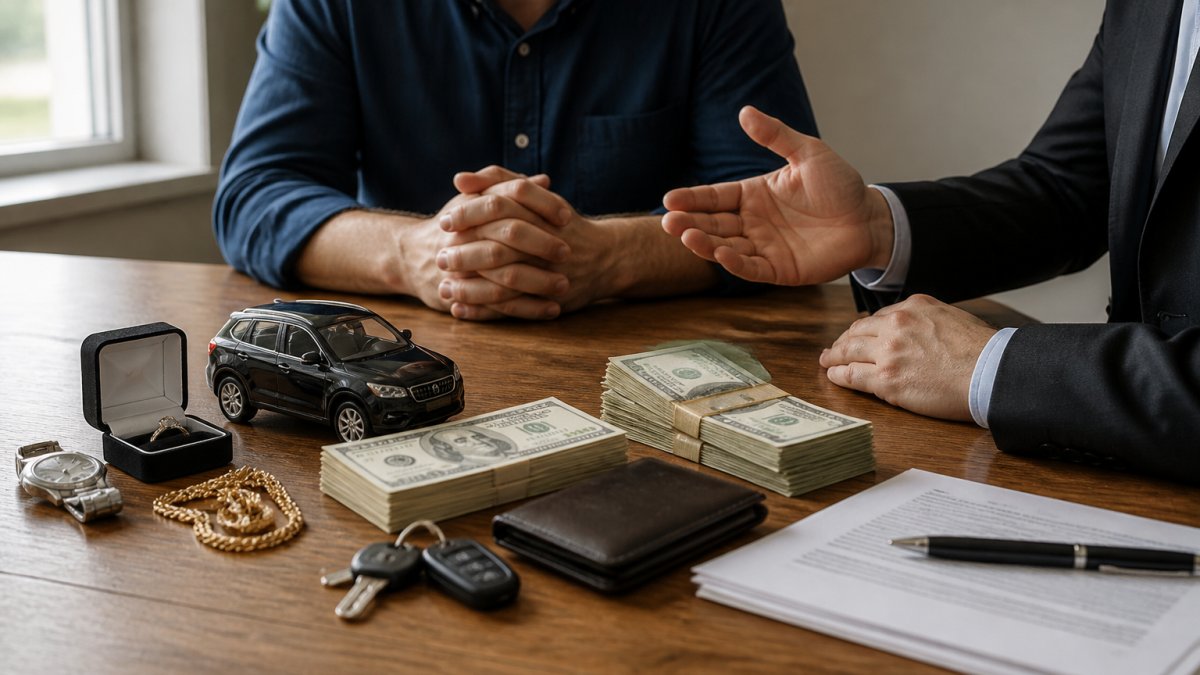
Bail agents evaluate collateral based on liquidity, verifiability, and market value. The most accessible alternatives fall into three categories: liquid funds, tangible property, and financial instruments.
Cash and Liquid Assets
Posting the full bail amount directly to the court is called a cash bond. The court holds the money until case resolution, then returns it if the defendant appears. This eliminates intermediaries and non-refundable fees but requires significant upfront capital tied up for months or longer.
Savings accounts, money market accounts, and certificates of deposit can be pledged. The bail agent verifies the balance and may require a lien or freeze. The key advantage is speed, no appraisal or title transfer required.
Vehicle Titles and Personal Property
A clear vehicle title can serve as collateral. The bail agent places a lien on the vehicle without requiring you to surrender the keys. Depreciation is a real concern; a vehicle loses 10-15% of value annually, which can complicate recovery if the defendant fails to appear.
Electronics, tools, equipment, and collectibles also qualify but require professional appraisal and secure storage, adding time and cost.
Jewelry, Stocks, and Securities
Jewelry and precious metals offer quick liquidity with professional appraisal and secure storage. Stocks, bonds, and brokerage accounts require minimal documentation but carry market volatility risk; if the stock market declines during the case, collateral value may drop below the bail amount.
How Much Do Bail Bonds Cost Without Property Collateral
The non-refundable premium, the fee paid to the bail agent, varies based on bail amount, defendant risk profile, and collateral type. The total financial burden extends beyond the premium itself.
Premium Structures by Collateral Type
Most states cap bail agent fees at 10-15% of the total bail amount. For example, a $5,000 bail might carry a $500-$750 premium, while a $50,000 bail could be $5,000-$7,500.
The collateral type affects the premium calculation:
Cash bonds carry the lowest risk; premiums may be 8-10%. Co-signer bonds typically command 12-15% because recovery depends on the co-signer's creditworthiness. Vehicle or personal property collateral falls in the middle (10-13%) but incurs storage fees of $50-$200 per month. Payment plan arrangements often include 5-12% annual interest; a $1,500 premium over six months at 10% interest costs an additional $75-$150.
Hidden Costs Beyond the Premium
Secondary costs accumulate: appraisal fees ($75-$300), collateral storage ($50-$150/month), payment processing fees ($25-$50 per transaction), and credit card cash advances (20-29% APR with no grace period). A $1,500 cash advance at 25% APR costs $187.50 in interest over six months.
Total Cost Comparison: Real Scenarios
For a $10,000 bail with a 12% premium ($1,200): Cash bond costs $0 but ties up $10,000 for 6-12 months. Co-signer bond costs $1,200 upfront. Vehicle collateral costs $1,200 + $600 storage = $1,800 over six months. Payment plan (6 months at 8% interest plus $30 processing fees) costs $1,428. Credit card cash advance (25% APR) costs $2,587.50 total and should be avoided.
Payment Plan Risks and Long-Term Cost
Payment plans spread cost over time but introduce financial risk. If the case extends beyond the payment schedule, the family may still be making payments months after release. Missing even one payment can trigger bond revocation and re-arrest. Families should ask: What is the total cost including all fees? What happens if the case lasts longer than the payment plan term? Is there a penalty for early payoff?
Comparing to Property-Based Collateral
Property collateral typically carries lower premiums (8-10%) but creates foreclosure risk. Non-property collateral avoids this catastrophic risk but costs more in total fees and interest. Understanding the true cost, premium plus storage, interest, processing, and appraisal fees, allows families to choose the least expensive available option.
Using a Co-Signer or Indemnitor
A co-signer, also called an indemnitor, is a third party who assumes financial responsibility for the defendant's appearance. This person doesn't need to own property.
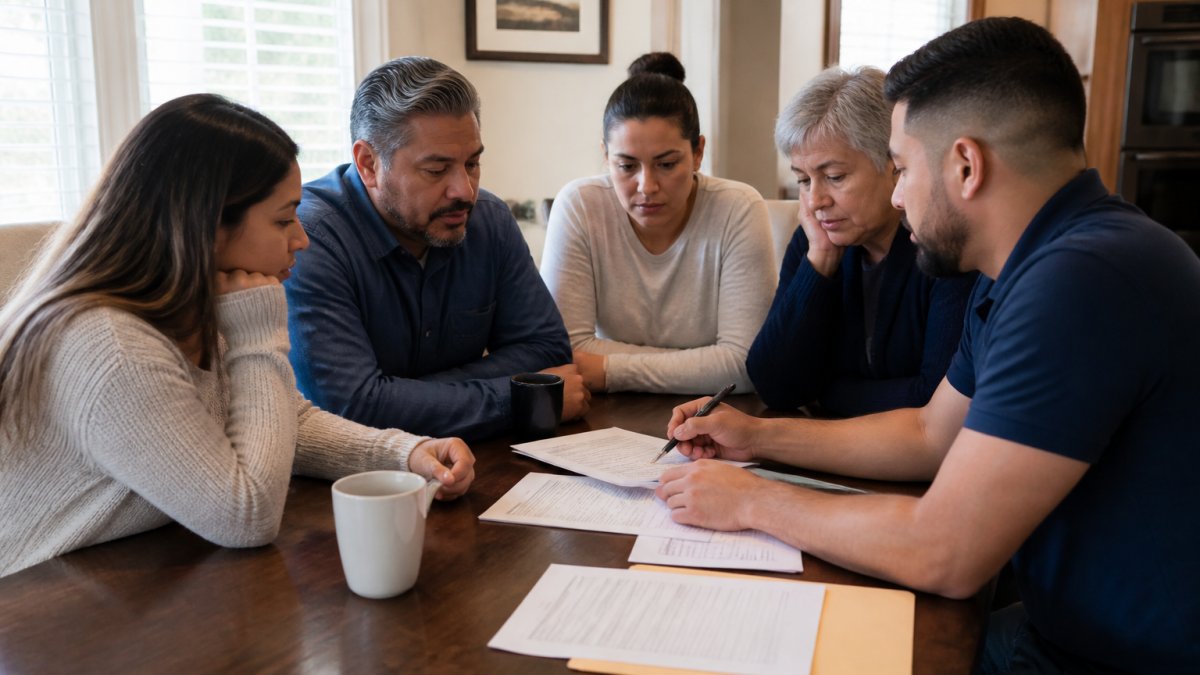
The co-signer's role is straightforward but serious. If the defendant fails to appear in court, the bail agent can pursue the co-signer for the full bail amount.
The advantage is clear: the defendant gets released without pledging personal assets. No vehicle title, no jewelry appraisal, no cash held by the court. The disadvantage falls entirely on the co-signer, who bears the financial risk.
Co-signer agreements typically involve a non-refundable premium paid upfront and a promissory note binding the co-signer to repay the full bail amount if the defendant doesn't appear.
Bail Bond Payment Plans for Flexible Financing
Payment plans spread the non-refundable premium over time, increasing accessibility for families without immediate liquid cash. A typical arrangement involves a down payment followed by monthly or bi-weekly installments. Missing payments can trigger bond revocation and re-arrest. Some agencies charge interest; others offer interest-free plans with stricter terms. National Bail Bond of Lubbock works with families to create realistic payment schedules that fit their circumstances.
Legal Alternatives: Bail Reduction and Release on Own Recognizance
Two legal pathways can eliminate the bail requirement: bail reduction hearings and release on own recognizance (OR). A bail reduction hearing allows a defense attorney to argue the bail amount is excessive based on community ties, employment, and flight risk. OR release means the defendant is released on a promise to appear with no bail or collateral. Both require legal representation and are worth pursuing when bail amounts seem unreasonable.
What to Know About Non-Property Collateral Risks
Non-property collateral introduces distinct risks that property-based arrangements don't carry. Understanding these risks prevents costly mistakes and family conflict.
Third-Party Liability: The Legal Obligation Behind Co-Signer Agreements
A co-signer signing a bail bond indemnity agreement becomes personally liable for the full bail amount if the defendant fails to appear. The bail agent can pursue the co-signer through direct collection, wage garnishment (up to 25% of disposable income), bank account levy, or property lien. A civil judgment damages credit for 7-10 years. Critically, the co-signer's liability exists even if the defendant's case is dismissed or results in acquittal. If the defendant fails to appear, regardless of reason, the co-signer owes the full amount. This is why family relationships have fractured over bail obligations.
Asset Liquidity Risk: Market Conditions and Forced Sales
Market conditions determine actual recovery value when collateral is liquidated. Stocks are volatile; a 15% market decline reduces proceeds significantly and incurs transaction fees and capital gains taxes. Vehicles depreciate 10-15% annually; a vehicle worth $12,000 when pledged may be worth $9,600-$10,200 when liquidated. Jewelry is subject to 30-50% dealer markups; a $5,000 appraisal may yield only $2,500-$3,500 in proceeds. Electronics and collectibles sell at 20-40% below appraised value. Families should assume they will recover 50-75% of appraised value for non-real estate collateral if forced liquidation occurs.
Collateral Recovery Timeline and Process
Unlike real property, where a lien can be enforced relatively quickly, non-property collateral recovery is slow and fragmented.
Vehicle recovery takes 2-4 weeks. The bail agent must file a lien release with the state motor vehicle department, arrange towing and storage, and then sell the vehicle through auction or private sale.
Jewelry and personal property recovery takes 4-8 weeks. The bail agent must arrange professional appraisal (if not already done), secure storage, and identify appropriate buyers or auction houses.
Promissory notes and personal loans from the co-signer are the slowest to recover. The bail agent must file a civil lawsuit, obtain a judgment, and then pursue collection through wage garnishment or asset seizure.
During this entire recovery period, the defendant remains in custody or on bond conditions. The family loses access to their collateral immediately but may not recover proceeds for weeks or months.
Payment Plan Default: Immediate Consequences
Payment plans are structured with strict terms. Missing a single payment, even by a few days, can trigger bond revocation.
When a payment is missed:
Day 1-3: The bail agent sends a notice of default, typically requiring payment within 3-5 days.
Day 5-7: If payment is not received, the bail agent files a motion to revoke the bond with the court.
Day 7-10: The court issues a warrant for the defendant's arrest. The defendant is re-arrested, often at home or workplace, creating public embarrassment and employment consequences.
Upon re-arrest: The defendant is held without bail pending a new bail hearing. The family has lost all payments made to date (non-refundable) and must post new bail or find a new bail agent.
This is not a minor inconvenience. A missed payment due to a payroll delay, illness, or administrative error can result in re-arrest and loss of all funds paid. Families should understand that payment plans require disciplined financial management and that the obligation continues even if the defendant's case is delayed or extended.
Comparing Risk Profiles: Property vs. Non-Property Collateral
Property collateral (real estate) carries lower premium costs but higher catastrophic risk. If the defendant fails to appear, the bail agent can foreclose on the home through a lien process, potentially resulting in loss of the family residence.
Non-property collateral carries higher premium costs but more immediate, fragmented recovery. The bail agent can liquidate assets quickly, but the family loses access to those assets immediately and may recover less than appraised value due to market conditions and dealer markups.
Co-signer arrangements carry no asset risk but maximum personal liability. The co-signer's wages, bank accounts, and credit can be affected for years. This is appropriate only when the co-signer fully understands the commitment and has confidence in the defendant's reliability.
The financial reality: all collateral arrangements carry risk. The question is not whether to avoid risk, but which type of risk the family can best manage.
Frequently Asked Questions
What can be used as collateral for a bail bond besides property?
Cash, vehicle titles, stocks, jewelry, and other valuable personal property can serve as bail bond collateral alternatives. A co-signer with good credit can also guarantee the bond without physical collateral. The specific assets accepted depend on the bail agent and the bond amount. Some agencies offer payment plans that reduce the need for upfront collateral entirely. Speak with a bail agent about which options work for your situation.
How much do bail bonds cost if I don't have property to pledge?
Bail bond costs typically involve a non-refundable premium, usually 10-15% of the total bail amount, regardless of collateral type. The actual cost depends on the bail amount set by the court, your creditworthiness, and the bail agent's assessment of risk. Payment plans can spread this premium over time with installments. Contact a bail agent directly for a quote based on your specific case, as pricing varies.
Are there payment plans available if I cannot provide collateral?
Yes, many bail agencies offer payment plans that allow you to pay the bond premium in installments rather than in full upfront. These structured arrangements typically involve a down payment followed by monthly or bi-weekly payments. Payment plans increase accessibility when immediate cash is unavailable, though they may require credit checks and come with conditions. Failure to maintain payments can result in bond revocation, so understand the terms before signing.
What happens to my collateral if the defendant fails to appear in court?
If the defendant fails to appear, the bail agent can forfeit the collateral to cover the full bond amount owed to the court. This means the bail agent may sell your vehicle, liquidate stocks, or pursue other assets pledged as security. The defendant's failure to appear triggers a forfeiture process, and you lose the collateral permanently. This is why understanding the legal and financial risks of third-party collateral is critical before agreeing to pledge assets.
Can I use a vehicle as collateral for a bail bond?
Yes, vehicle titles are commonly accepted as bail bond collateral if the vehicle is paid off and the title is clear of liens. The bail agent holds the title until the case concludes and the defendant meets all court obligations. The vehicle's value is appraised to determine if it covers the bond amount. However, you risk losing your vehicle and transportation if the defendant fails to appear in court, so weigh this risk carefully.